

Chime – Mobile Banking
4.8

I’d consider Chime – Mobile Banking most useful when one person wants a clear, phone-based way to manage everyday money, but a household can also benefit from the routine it encourages. Picture a shared evening at home: one person checks whether a paycheck has arrived, another is planning groceries, and both need to keep their own spending decisions straight. Chime can help the account holder stay on top of activity, but I would treat it as an individual banking app, not a shared household dashboard. That distinction matters when several people use the same device or coordinate bills.
Keep account access personal, even on a shared device
If a phone is passed between partners, relatives, or roommates, I would not treat that convenience as a reason to share banking credentials. An account should remain under the control of its owner, and each person should use their own access rather than relying on a communal login. This is a practical boundary, not a judgment about trust: banking screens can expose balances and transaction details, and a shared device can make it harder to know who is responsible for a change.
Before signing in on a household phone, think through who can unlock it and whether notifications might be visible to other users. For a personal phone, I’d keep the device secured and pay attention to where account alerts appear. If you need to review a purchase together, show the relevant information deliberately rather than leaving the account open. That simple habit helps preserve privacy without making ordinary bill planning awkward.
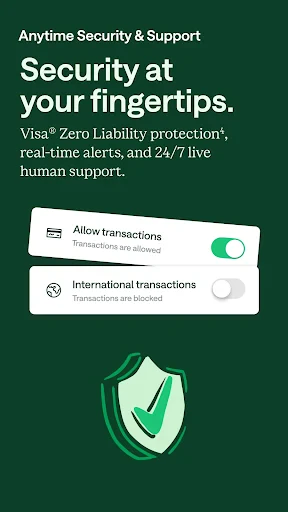
The app’s card-blocking option is also useful to think about as part of a household plan. If the card is misplaced while someone is out, the account holder can act from the app instead of waiting until they are home to look for it. I would still keep the account holder responsible for deciding when to block the card and for checking what happened afterward; another person’s good intentions do not replace clear account ownership.
Coordinate bills without confusing responsibility
Chime can support a household routine by giving its account holder a place to check incoming money and transaction activity. It does not, by itself, settle who owes what or make shared expenses fair. I would pair it with an agreed method for recording rent, utilities, groceries, and reimbursements, especially when bills are split unevenly. A short note or a separate budget record can prevent a quick balance check from being mistaken for a complete picture of the household’s finances.
For example, if a paycheck arrives before a grocery run, the account holder can check the available balance and decide what fits the week’s plan. If another household member is contributing, agree beforehand on the amount and timing rather than assuming that an alert or deposit means money is available for everyone. This avoids a common source of friction: seeing money in an account and treating it as shared before the people involved have agreed on its purpose.
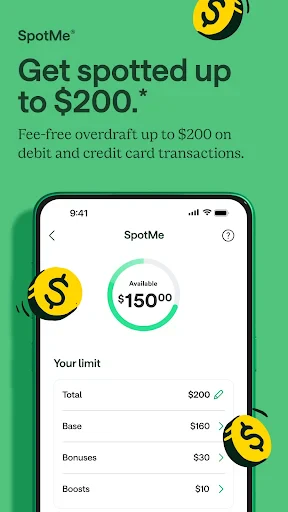
Early direct deposit can help with timing, but I would not build a bill schedule around money arriving early every pay period. A household still needs a fallback for due dates and essentials if a deposit arrives on its regular schedule. Likewise, fee-free overdraft may provide a cushion in eligible circumstances, but it should not become a routine spending plan. The best use is as a safety net, while the regular budget accounts for the money you know is there.
Age, trust, and who should choose another option
The app is marked for Everyone, but that content rating is not the same thing as a promise that every age group can independently open or manage an account. I would check the account-opening requirements that apply to the person who wants to use it, rather than assuming the age label answers that question. For a younger family member, a parent or guardian should make sure the arrangement fits the person’s age and needs, and should not hand over an adult’s login as a shortcut.
Trust is important, but so is having a clear record. If two adults want to manage shared money jointly, they should first decide whether an individual account suits that arrangement or whether an account designed for joint ownership would be a better fit. Chime’s convenience does not remove the need to agree on who owns the account, who can access funds, and how each person will track contributions. Someone who needs formal joint controls should compare options specifically on that point.
I would also look elsewhere if your main goal is a detailed household budgeting system, broad branch-based service, or a single view of several people’s accounts. A conventional bank may suit someone who values in-person help or needs a particular account structure; a dedicated budgeting tool may be more appropriate for categorizing shared costs across accounts. Those alternatives can involve different trade-offs, but they may fit better than asking one mobile banking app to solve coordination problems it was not built to handle.
Hey there! So, I recently got my hands on the Chime – Mobile Banking app, and let me just say, it’s quite the game-changer for managing finances right from your phone. If you’re tired of traditional banking hassles, you might want to stick around and hear what I’ve got to share.
Getting Started with Chime
Diving into the Chime – Mobile Banking app was as smooth as butter. Signing up was a breeze, and in just a few taps, I was all set up. One thing I noticed right off the bat is how user-friendly the interface is. Everything is laid out intuitively, so whether you’re a tech whiz or just tech-curious, you’ll feel right at home.
Features that Stand Out
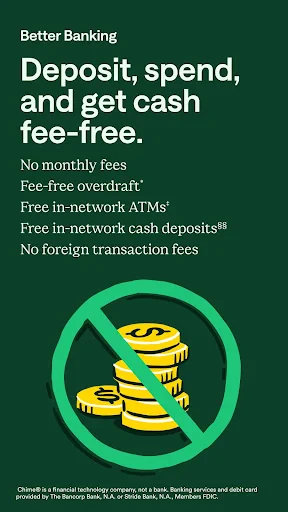
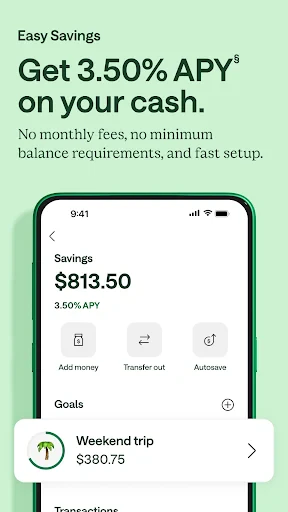
Now, let’s talk features. Chime offers a no-fee banking experience, which is honestly a breath of fresh air. Say goodbye to those annoying monthly fees and hidden charges. Plus, it has an automatic savings feature that rounds up your purchases to the nearest dollar and stashes the change away. It’s like a digital piggy bank that works without you even noticing!
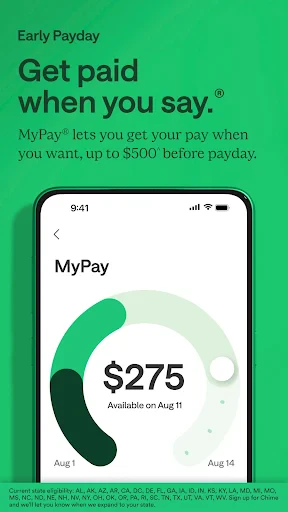
Another highlight is the early direct deposit feature. You can get your paycheck up to two days early. It’s perfect for those of us who might need a little cash flow boost before the weekend hits. And, if you’re like me and often forget to check the balance, Chime sends you real-time transaction alerts. It’s like having a personal finance assistant in your pocket.
Turning helpful features into habits
The automatic savings idea works best when you already know what the spare change is for. I’d give it a purpose—an emergency buffer, a planned purchase, or a future bill—rather than treating each small transfer as money that has disappeared. The round-ups can make saving feel low-effort, but they are still moving money you may need for spending. If your balance is tight near payday, I’d prioritize essentials first and avoid relying on an automatic habit to decide what is affordable.
Transaction alerts are most useful when they prompt a quick check, not when they become background noise. I’d leave them on while learning how money moves through the account, then pay attention to whether each notification helps me spot an unfamiliar charge or simply interrupts the day. When something looks wrong, reviewing the transaction promptly is more useful than assuming an alert itself resolves the issue. The app can make activity easier to notice; the account holder still has to follow up.
The early-pay feature is a timing convenience rather than extra income. If a paycheck appears ahead of its usual date, I’d resist shifting every recurring bill earlier or spending as though the next pay cycle has also moved. Keeping a small calendar of due dates alongside the app’s balance helps distinguish “money arrived” from “money is free to spend.” That is especially helpful when several household costs fall close together.
Where it fits among banking choices
As a finance app, Chime sits in the mobile-first part of banking: it makes routine checks and account activity convenient without asking you to visit a branch for everyday tasks. Compared with a traditional bank app, its appeal is the emphasis on a straightforward digital routine and avoiding monthly fees. The trade-off is that people who depend on face-to-face assistance, a particular joint-account arrangement, or a wider set of services should compare their needs carefully rather than choosing based on convenience alone.
It also differs from a standalone budgeting app. A budgeting tool may be better for planning categories across multiple accounts or tracking a household’s shared spending, while Chime is centered on banking activity for its account holder. I would not expect one balance screen to explain the whole household’s position. If you use a separate budget, treat Chime’s transactions as one input and reconcile them with cash spending, other accounts, and any expenses another person paid.
Chime is free to download, developed by Chime, and has an average rating of 4.8 from around 975,000 ratings, with roughly 230,000 written reviews and over 10 million installs. It was released on March 28, 2014; version 5.310.1 requires Android 10 or later, and its age rating is Everyone. Those figures suggest broad interest, but they do not tell me whether its account setup or day-to-day approach will suit a particular person. I’d make that decision by comparing the way I actually handle deposits, bills, and shared costs.
The Skinny on Security
With all this talk about online banking, security is probably a top concern, right? Chime takes security seriously. They use encryption to protect your data, and the app allows you to instantly block your card if it’s lost or stolen. That’s a huge relief and definitely adds peace of mind when you’re out and about.
A Few Thoughts to Wrap Up
In the world of digital banking, Chime is making waves for all the right reasons. It’s simple, efficient, and genuinely feels like it has the user’s best interests at heart. Whether you’re looking to shake off those pesky fees or just want a more streamlined way to handle your money, Chime might just be worth your time.
So, if you’re looking for a modern take on banking that fits right in your pocket, give Chime a shot. It’s made my financial life a whole lot easier, and I bet it could do the same for you.
My household verdict is that Chime makes the most sense for an adult who wants mobile access, appreciates transaction visibility, and can keep account ownership and spending boundaries clear. It can make payday routines and quick checks less cumbersome, but it is not a substitute for a shared budget, a joint-account agreement, or careful planning around due dates. I’d choose it for straightforward personal banking and look at a different arrangement when several people need formal, shared control over the same money.
4.8
229.51K Reviews
Pros
- No monthly fees or overdraft charges.
- Early direct deposit access.
- User-friendly interface.
- Free ATMs within their network.
- Real-time transaction alerts.
Cons
- Limited cash deposit options.
- No physical bank branches.
- Not ideal for cash-heavy users.
- International fees may apply.
- Requires stable internet connection.


